
Finance used cars in India can be simpler when you separate the car decision from the loan decision. A used-car loan can spread the purchase cost into monthly EMIs, but the right choice depends on the car’s value, your repayment capacity, loan costs, and the lender’s terms.
Finance Used Cars in India: How the Process Works
The usual process is straightforward: choose a car, check its valuation and eligibility, compare loan offers, submit documents, complete verification, pay your required contribution, and complete the loan agreement. The financed amount may not equal the seller’s asking price because lenders can base financing on their own valuation and lending limits.
For example, if a used car is listed for ₹7 lakh, the lender may calculate finance on an eligible value or percentage rather than automatically funding the full ₹7 lakh. The amount you need to pay upfront can therefore be higher than expected. Check the approved loan amount before finalizing the purchase.
How Much Does It Cost to Finance Used Cars?
The easiest way to compare a used-car loan is to look at the complete cost, not just one number.
Think of the loan in this order:
Loan amount → Interest rate → Tenure → EMI → Total repayment → Extra fees
Here is what each part means:
| Loan factor | What it tells you | Why it matters |
|---|---|---|
| Loan amount | How much you borrow | A larger loan usually means more interest |
| Interest rate | Cost charged on the loan | A higher rate can increase both EMI and total repayment |
| Tenure | How long you repay | Longer tenure can lower EMI but may increase total interest |
| EMI | Monthly repayment | Helps you check whether the loan fits your monthly budget |
| Total repayment | Amount paid over the loan term | Shows the real cost more clearly than EMI alone |
| Fees and charges | Additional loan costs | Can make two similar-looking offers cost different amounts |
For India, the RBI Key Facts Statement framework provides borrowers with key loan information, including the all-in cost for applicable regulated lending. Read the KFS and final loan agreement before accepting an offer.
For example, consider a ₹6 lakh loan at 12% for 48 months:
- Approximate EMI: ₹15,800 per month
- Approximate total repayment: ₹7.58 lakh
- Approximate interest component: ₹1.58 lakh
Now change only the tenure. A longer term can make the monthly EMI easier to manage, but the total interest can rise. That is why comparing only the EMI can give you an incomplete picture.
The same principle applies when comparing lenders. One offer may show a lower rate but have different fees or terms. Another may have a higher EMI but a shorter tenure and lower overall interest.
Eligibility and Documents for a Used Car Loan
Eligibility normally depends on the lender’s current rules and can include age, income, employment or business profile, credit history, existing obligations, and other criteria. Requirements vary across lenders, so check the official eligibility conditions before applying.
Common documents may include identity and address proof, income documents, bank statements, photographs, and vehicle or seller documents. The exact list depends on the lender and applicant profile.
The vehicle also matters. Lenders may consider its age, condition, valuation, and whether the transaction meets their lending rules. Qualifying as a borrower does not automatically mean every used car will receive the same financing.
How to Compare Finance Options
You may find financing through a bank, NBFC, dealer, or online used-car platform. Instead of asking which option is “best,” compare the terms that actually affect your purchase.
| Option | Compare these factors | Key question |
|---|---|---|
| Bank | Rate, tenure, LTV, fees, eligibility | What is the total amount I will repay? |
| NBFC | Rate, approval process, fees, vehicle rules | How do the terms change for this car? |
| Dealer/platform | Convenience, partner lenders, bundled costs | Can I compare this offer with an outside option? |
A practical approach is to check your eligibility and possible loan amount first. Then compare at least the interest rate, tenure, total repayment, fees, down payment and vehicle conditions before choosing.
A larger down payment reduces the amount you borrow, but it also uses more of your available cash. A longer tenure may reduce the monthly EMI, while potentially increasing total interest. The right comparison depends on both your budget and the used car you are buying.

Steps Before Signing the Loan
Before accepting finance, check:
- The loan amount against the car’s agreed price and lender valuation.
- EMI, tenure, interest rate and total repayment.
- Processing, documentation and other applicable charges.
- Prepayment or foreclosure conditions.
- The KFS and final loan agreement.
- Vehicle ownership and registration documents.
- Whether insurance or other add-ons are optional or required.
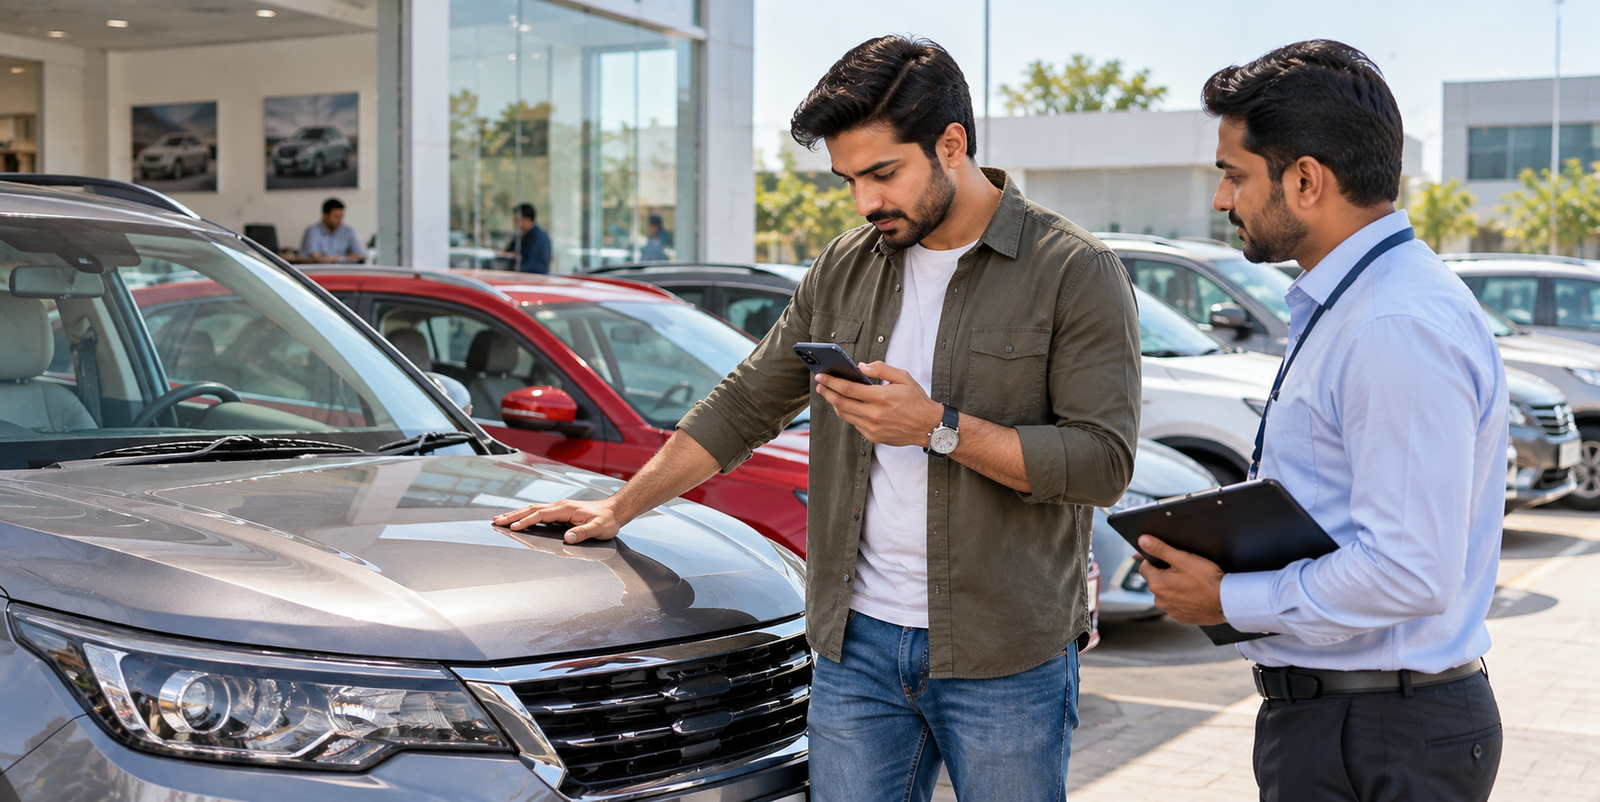
Also inspect the car independently. Loan approval does not confirm that the vehicle is mechanically sound or fairly priced.

Conclusion
Finance used cars decisions become easier when you compare the complete deal rather than focusing only on the monthly EMI. Check the vehicle’s valuation, loan amount, down payment, total repayment, fees, eligibility and loan terms. For an India-based purchase, use current official lender information and read the KFS before signing. The goal is to choose financing that fits both the car and the amount you can comfortably repay.
